A document from an insurer confirming a vendor holds liability coverage at stated limits for a date.
Read the transcript
COI (Certificate of Insurance).
A document from an insurer confirming a vendor holds liability coverage at stated limits for a date.
How it works in practice.
A certificate of insurance is a one-page summary issued by a vendor's broker or insurer.
It names the insured business, the insurer, the policy number, the policy dates and the limits, usually for commercial general liability (CGL).
In Ontario and the GTA.
Hotels and convention venues across the GTA ask for COIs from every outside vendor: AV, décor, entertainment, rentals and caterers.
Limits of 2 dollars million CGL are typical, with some venues asking for 5 dollars million for rigging, staging or pyrotechnic work.
How to handle it.
Get the venue's exact insurance wording at contract stage: limit, additional insured name and address, and any special endorsements.
Send that wording to every vendor with their contract, not the week of the event.
More detail, examples and common mistakes are on this page, below the video.
How it works in practice
A certificate of insurance is a one-page summary issued by a vendor’s broker or insurer. It names the insured business, the insurer, the policy number, the policy dates and the limits, usually for commercial general liability (CGL). For events, the venue often wants to be named as an additional insured, which means the vendor’s policy will defend the venue too if a claim arises from that vendor’s work.
A COI is evidence, not the policy itself. It tells you coverage existed on the day it was issued. Check that the policy dates span your event date, that the named business matches the business on your contract, and that the limit meets what the venue asked for.
In Ontario and the GTA
Hotels and convention venues across the GTA ask for COIs from every outside vendor: AV, décor, entertainment, rentals and caterers. Limits of $2 million CGL are typical, with some venues asking for $5 million for rigging, staging or pyrotechnic work. A host who needs their own cover can buy one-day event liability; a typical GTA range for $2–5 million limits is $150–$400 (2026). Venues set their own requirements, so always work from the venue’s written list.
How to handle it
- Get the venue’s exact insurance wording at contract stage: limit, additional insured name and address, and any special endorsements.
- Send that wording to every vendor with their contract, not the week of the event.
- Check each COI on arrival: business name, dates, limit, additional insured.
- Log the COIs on your vendor contact sheet with expiry dates.
- Forward the complete set to the venue at least two weeks out.
- For rigging and aerial acts, confirm the rigger’s own insurance as well as the performer’s.
Questions to ask
- Does the policy cover the activity being performed, such as aerial work or fire, or does it exclude it?
- Is the venue named exactly as its legal entity, not its trade name?
- Does the vendor carry liquor liability if they are serving alcohol?
A vendor who cannot produce a COI within a few days is telling you something about how they run their business. The performer tech rider template includes an insurance line so it is requested up front.
Why it matters
Venues require COIs from vendors; collect them with contracts, not the week of.
Example
A performer's COI showing $2 million CGL naming the venue as additional insured.
Common mistakes
- Accepting a COI that expired before the event date
Related guides, venues and vendors
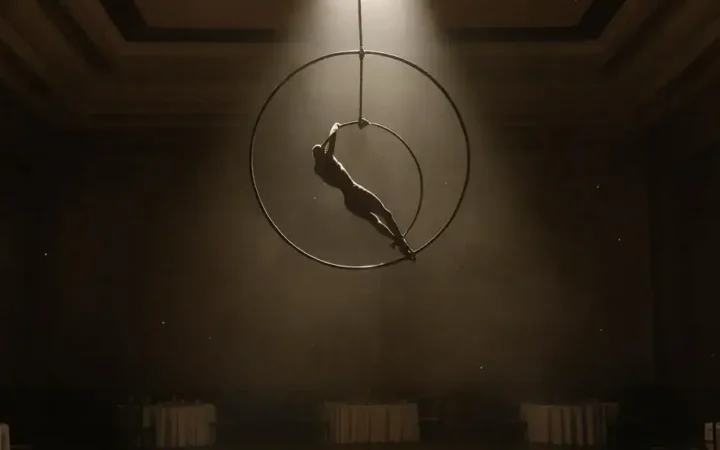
Lyra
Entertainment
A suspended steel hoop used for aerial performance.
Read more
Headliner
Entertainment
The main act of a program, placed at the moment of peak attention.
Read more
Special Occasion Permit
Safety & Permits
The AGCO permit required to sell or serve alcohol at an event in an unlicensed location in Ontario.
Read more